PowerCurve Originations
Combine Zenoo's onboarding flows with Experian PowerCurve Originations for automated credit decisioning at the point of application.
At a glance
Overview
PowerCurve Originations overview
PowerCurve Originations is Experian's decisioning platform for credit originations. It combines bureau data, scores, and affordability signals with configurable decision strategies, so lenders can approve, refer, or decline applications automatically at the point of application. Through Zenoo it runs as a pre-built connector: identity verification and compliance checks feed the credit decision in one flow.
- Company
- Experian
- Category
- Credit risk scoring
- Strongest in
- Bureau-backed credit decisioning at origination
- Best fit
- Lenders automating application decisions
Where it is strongest
Key strengths
What PowerCurve Originations does well.
Bureau data at the decision point
Decisions draw directly on Experian's credit data and scores, one of the deepest bureau datasets available.
Configurable decision strategies
Risk teams can define and adjust approve, refer, and decline strategies without rebuilding the integration.
Built for origination volume
The platform is designed for automated decisioning across consumer and SME lending at scale.
Who it suits
Best for
Where PowerCurve Originations fits, and what to plan for.
Honest notes on the trade-offs, each with a way to cover the gap inside a Zenoo flow.
- Lenders automating origination decisions with bureau data
- Banks combining credit risk and affordability checks at application
- Risk teams that want to own decision strategies without engineering changes
- Credit decisioning, not identity verification. PowerCurve decides creditworthiness. Identity, document, and AML checks come from other providers, which is exactly what a Zenoo flow adds around it.
- Enterprise implementation. It is an enterprise decisioning platform, so deployment and strategy design take planning. The pre-built Zenoo connector removes the integration part of that work.
- Quote-based pricing. There is no public pricing; commercial terms depend on data and volume requirements.
Open the customer's case
What your team sees
The PowerCurve Originations result, beside everything else.
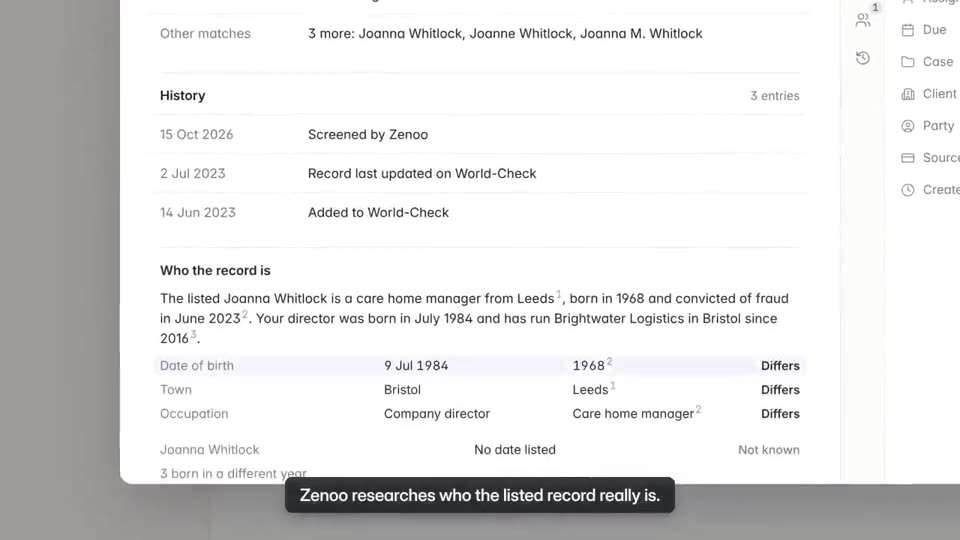
The result sits with screening and review on one case, so nobody checks a second tool to see the whole customer.
What you can build
- Automated approve, refer, and decline decisions in loan onboarding
- Affordability and credit checks after identity verification
About PowerCurve Originations
FAQs
PowerCurve Originations questions.
How does PowerCurve work with Zenoo?
Through a pre-built connector. Configure it in no-code Studio, add fallback logic, and get one contract and a unified audit trail across every provider in the flow.
What is PowerCurve Originations used for?
Automating credit decisions at the point of application. It combines Experian bureau data, scores, and affordability signals with decision strategies your risk team controls.
Does PowerCurve verify identity?
No, it decides creditworthiness. In a Zenoo flow, identity verification and AML screening run first, then the verified application passes to PowerCurve for the credit decision.
Hands it to your team
Verification is the first step. Compliance Hub handles the rest.
Once a customer is verified, screening and review happen in Compliance Hub. A possible PEP match lands in your team inbox with the evidence and the full history beside it. Zenoo suggests, your team decides.
Pairs well with
 SumsubScreen the applicant for sanctions and PEPs before the credit decision.TR
 TrueLayerAdd open banking income and affordability data to the decision.CO
 ComplyAdvantageScreen applicants for sanctions and PEP status in the same flow.
Alternatives
More in credit and risk scoring
Tomorrow, your case
Bring us a case that went wrong.
We will run it through Zenoo while you watch: the evidence, the decision, and the record your MLRO would want to defend.
30 minutes. Your data. No slides.