Brokers send us half-finished cases, and compliance spends the day chasing.
With ZenooEach case lists exactly what is outstanding. Missing documents are requested through the client portal, and quiet customers are reminded for you.
Lending · Business and asset finance
Borrowers and the people behind them checked on one case, whether the application comes from a broker, your own team or your website. Zenoo reads the register, brings in your data vendors' results and asks only for what is missing. Your credit team sees a clean file.
30 minutes. Your data. No slides.
Business lenders, asset finance and specialist lenders.
A company borrower, its directors and owners, often sent in by a broker.
Beneficial owners, register discrepancies, and keeping checks up to date.
Sound familiar?
Brokers send us half-finished cases, and compliance spends the day chasing.
Every extra question up front loses us applicants.
Each market runs KYC its own way, on spreadsheets and email.
Existing customers come back for a new facility and we start from scratch.
One case, start to finish
Follow one business borrower through Zenoo, from the broker's submission to the approval your credit team waits for.
Nothing is cleared or added on its own.
Product screens show fictional data.
Watch it work · 0:52
Where this fits
The broker's application comes in through the API. Your screening and ID providers send their results to the same case, and anything that needs a person goes to the Inbox. Pick providers from the Marketplace, or bring your own.
Your checksFrom the Marketplace
My inbox0 done
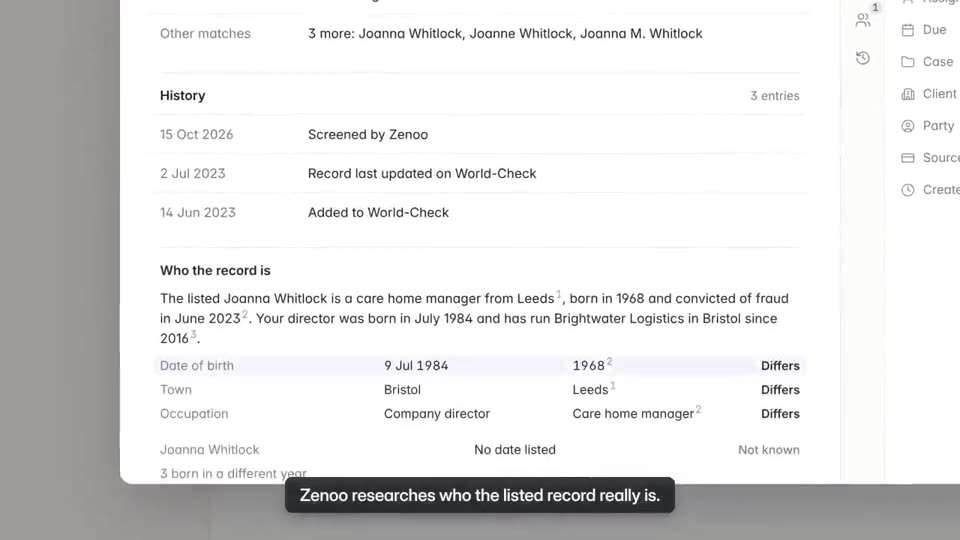
Zenoo suggests. You decide.
What the rules ask
| What the rules ask | Where it lives in Zenoo |
|---|---|
| UK MLR 2017, regulations 27 and 28Identify and verify the customer before you establish the relationship, and understand its purpose. | Identity, registry and screening checks run on one case, and nothing is approved while any check is still open. |
| UK MLR 2017, regulation 28For a business borrower, identify the beneficial owners and understand who controls it. | Owners and controllers are read from the register onto one structure and screened, people and companies alike. |
| UK MLR 2017, regulation 30ACheck the register, and report material discrepancies with what the customer told you. | What the broker or customer declared is compared with the register, and every difference is flagged for a person to review. |
| UK MLR 2017, regulation 28(11)Keep due diligence up to date for as long as the relationship lasts. | The structure and the last decision stay on the customer, and a change on the register lands in your inbox. |
| UK MLR 2017, regulation 40Keep records of the checks and the reasons for each decision. | Every decision, reason and change is kept in the case history with who made it and when, and nothing can be edited or removed. |
Last reviewed 21 October 2026. Each source links to the official text. A summary to help you compare, not legal advice. Your MLRO sets the policy. Zenoo runs it and keeps the record.
Zenoo AI
On a borrower's case, Zenoo reads the register, the submission and the screening results, and suggests the next step with its sources. A person makes every call.
Getting live
Send applications in through the API, or onboard customers through Zenoo's own journeys. Keep the data vendors you have, under your contracts, and add others from the Marketplace.
Browse the MarketplaceFour to six weeks to production is typical, depending on your providers and systems. It starts with a demo on a case you bring, then a pilot on real cases.
How buying worksIn the EU or US region, or on a dedicated UK tenant. Encrypted with AES-256 at rest and TLS 1.3 in transit. ISO 27001 certification is in progress.
Trust and securityQuestions
In the UK, lending is one of the activities the Money Laundering Regulations cover, so lenders apply customer due diligence to borrowers and the people behind business borrowers. Your MLRO decides how this applies to your business.
Yes. Applications arrive through the API, whether they start with a broker, your own team or your website, and each one becomes a case with the same checks.
Zenoo reads the register first, so borrowers are not asked for what is already there. Missing documents are requested through the client portal, and quiet customers are reminded for you.
Yes. Zenoo runs checks with the providers you already use, under your contracts, and you can add local providers for other markets from the Marketplace.
No. Zenoo suggests the next step with its sources. A person clears every hit and approves every file, and both are on the record.
No. Zenoo covers the compliance checks on the borrower and the people behind it. Your credit process stays your own.
Tomorrow, your case
We'll run it from submission to approval while you watch.
30 minutes. Your data. No slides.


