Sixteen parts
What KYB verification is (and how it differs from KYC)
KYB, short for know your business, is the process of confirming that a business customer, supplier, or partner is real, legally registered, and who it says it is, then identifying the people who own and control it and checking that none of them are sanctioned, high risk, or hidden. It is the corporate counterpart to KYC (know your customer): where KYC verifies an individual, KYB verifies a legal entity and then runs KYC on the humans behind it. For the definition and how the two compare, see what is KYB.
KYB answers four questions in sequence: does this business legally exist, who owns and controls it, are any of those parties a financial-crime risk, and how risky is the relationship overall. It is required by the same anti-money-laundering frameworks that require KYC. Globally the standard-setter is the Financial Action Task Force (FATF): Recommendation 10 sets customer due diligence for legal persons, and Recommendations 24 and 25 govern transparency of beneficial ownership of legal persons and legal arrangements.
Common misconception
A name match is not ownership verification
The company name and number match the registry, so the business is verified.
A registry match confirms the entity was registered. It says nothing about who ultimately owns and controls it. Verifying the company is the easy half of KYB. The reason KYB cases run so much longer than individual KYC is tracing ownership up through holding companies, trusts, and cross-border layers, then running KYC on each ultimate beneficial owner at the top.
The seven steps to verify a business
This is the ordered process. Steps 1 to 2 establish the entity. Steps 3 to 4 establish the people. Steps 5 to 6 assess risk. Step 7 keeps it true over time. Most competitor guides stop at a six-step product flow and fold ownership and screening into single bullets. The value here is treating ownership discovery, UBO verification, and ongoing review as distinct, non-trivial steps.
- Collect and confirm the business's core identity. Gather legal name, registration number, jurisdiction, incorporation date, registered address, legal form, and current status, and confirm internal consistency before checking any external source.
- Verify against authoritative registries, and know each source's limits. Confirm the data against official company registries, remembering that a registry records what was filed, not what is true.
- Map the ownership and control structure. Diagram how ownership flows upward through direct shareholders, intermediate holding companies, parents, trusts, and foundations, and identify the directors and senior managers.
- Identify and verify the ultimate beneficial owners (UBOs). Find the natural people who own 25 per cent or more (the ownership prong) or who otherwise control the entity (the control prong), unwinding layered structures.
- Screen the business and its owners, directors, and officers. Run sanctions, PEP, adverse-media, and watchlist checks against the entity and every person identified in steps 3 and 4.
- Risk-assess the business, and decide if EDD is triggered. Score the relationship on a risk-based approach and apply enhanced due diligence where jurisdiction, industry, or structure raise the risk.
- Monitor continuously, and refresh on events, not just the calendar. Re-screen and watch for registry changes so a material change re-opens the case, and keep an audit trail of every check and decision.
Step 1. Collect and confirm the business's core identity
Gather the entity's foundational identity data and confirm internal consistency before checking any external source. The core fields are the legal name (and any trading or doing-business-as names), the registration or company number, the jurisdiction of incorporation, the incorporation date, the registered address (and principal place of business, which is often different), the legal form (limited company, LLC, partnership, sole trader, trust, or foundation), and the current status (active, dormant, dissolved, in liquidation, or struck off).
Common misconception
An EIN or tax number is not proof of incorporation
The business gave us its EIN, so its existence is confirmed.
In the US an EIN only proves IRS tax registration, not that the entity legally exists in a state. Incorporation must be confirmed against the relevant Secretary of State registry. A tax number is a data point, not evidence that a company was ever formed.
Step 2. Verify against authoritative registries (and their limits)
Confirm the step 1 data against official company registries. The mechanism is the same everywhere; the data quality is not. The honest takeaway to teach is that a registry match confirms a company was registered, not that its filed data is true. Treat the registry as a starting point, then corroborate with independent data (financials, web and operational footprint, licences) and, where the regime now allows, the verified identity of the people behind it.
| Region and source | What it confirms | Key limitation |
|---|---|---|
| UK: Companies House | Free, comprehensive, machine-readable record of registration, directors, and persons with significant control | Historically unverified. Companies House itself states it does not verify the accuracy of information filed. Identity verification is now being phased in under ECCTA. |
| US: Secretary of State | State-level incorporation and status, one database per state | No national register. Each of the 50 states plus DC has its own format, fields, and fees, so a business operating nationally may have filings across dozens of states. |
| EU: national registers via BRIS | Each member state's business register, interconnected through the Business Registers Interconnection System | Beneficial-ownership access has been turbulent and is transposed unevenly member state by member state (see step 4). |
| Beyond | Local company registers, where they exist and are accessible | Registration-number formats and data availability differ by country, so no single source or format works everywhere. |
Step 3. Map the ownership and control structure
Map the corporate tree before hunting individuals. Pull the shareholder register and the register of directors and officers, then diagram how ownership flows upward: direct shareholders, intermediate holding companies, parents, and any trusts or foundations in the chain. Identify who the directors, officers, and senior managers are, because control is not only about equity. This map is what turns "who owns 25 per cent" from a lookup into an actual calculation, because ownership through a chain has to be multiplied through each layer.
Step 4. Identify and verify the ultimate beneficial owners (UBOs)
The UBO is the natural person who ultimately owns or controls the business. This is the step that defines KYB and the step competitors treat most thinly. For the full detail, see ultimate beneficial ownership.
Under the US CDD Rule, a covered financial institution must identify each individual who directly or indirectly owns 25 per cent or more of the equity (the ownership prong) and one individual with significant responsibility to control the entity (the control prong). The EU AML Regulation harmonises a 25 per cent threshold, and FATF frames 25 per cent as a common line rather than an absolute one. Some jurisdictions and higher-risk cases use lower triggers, as low as 10 to 20 per cent in places such as Singapore and Hong Kong. State it plainly: 25 per cent is the common threshold, not a universal law, and firms should go below it on a risk-sensitive basis.
Both prongs are required. A person can be a UBO through control (senior management, a nominee arrangement, or a shareholder agreement) even with no qualifying equity. Where ownership runs through holding companies, you multiply the percentages through each layer to find who crosses the threshold at the top. Nominee directors and shareholders act as stand-ins for the true owner, and trusts separate legal ownership from beneficial interest, so the registered names are not the beneficial owners.
Note
The register you check may be closed or thin
In the EU, the Court of Justice struck down general public access to beneficial-ownership registers in November 2022 on privacy grounds; AMLD6 restored access on a legitimate-interest basis, but transposition is uneven and the European Commission opened infringement proceedings against 11 member states in 2025. In the US, FinCEN issued an interim final rule in March 2025 exempting US-formed entities from beneficial-ownership reporting, leaving only foreign reporting companies in scope. Both positions are fast-moving and worth re-checking at the point of use.
Step 5. Screen the business and its owners and directors
Run screening against the entity and every person identified in steps 3 and 4. Sanctions screening covers both the business and its owners and controllers against OFAC, UK OFSI, the EU consolidated list, UN, and other relevant lists, because a sanctioned UBO can taint an otherwise clean-looking company. PEP screening covers politically exposed persons among the UBOs, directors, and officers, applying enhanced due diligence where a match is a true match. Add adverse-media checks on the entity and the individuals, and any watchlist, enforcement, or debarment lists relevant to the sector.
The point competitors under-make is that screening the company alone is not enough. The ownership work in step 4 exists so that screening reaches the humans, which is where sanctions and PEP exposure actually sits.
- Sanctions screening of the business and of each owner and controller
- PEP screening of UBOs, directors, and officers
- Adverse-media screening of the entity and the individuals
- Sector-relevant watchlist, enforcement, and debarment checks
Step 6. Risk-assess the business (and EDD triggers)
Apply a risk-based approach, scoring the relationship on FATF's four risk dimensions: customer, country, product or service, and delivery channel. Practical factors that raise risk include incorporation or operation in a high-risk or FATF grey or black-listed country or a secrecy jurisdiction; a cash-intensive, high-value-goods, crypto, gambling, or money-services industry; structural complexity such as many layers, cross-border chains, trusts, or nominee arrangements; and shell-company red flags such as no physical premises or employees, minimal online presence, a registered-agent-only address, or activity inconsistent with the stated business.
Where risk is high, enhanced due diligence (EDD) is triggered: source-of-funds and source-of-wealth checks on UBOs, deeper ownership verification, financial statements, senior management sign-off, and more frequent review. Low-risk cases may qualify for simplified due diligence with documented reasoning.
Step 7. Monitor continuously and refresh on events
One-off KYB decays. Directors change, ownership is restructured, a UBO becomes sanctioned, a company is struck off, and adverse media appears. A verification that was accurate at onboarding can be wrong within weeks, which is why regulators and vendors are moving from periodic reviews to continuous, event-driven monitoring, the perpetual-KYC pattern applied to businesses. Build re-screening and registry-change monitoring so a material change re-opens the case automatically, and keep an audit trail of every check and decision, because one-time verification is no longer treated as sufficient. Record retention is typically a minimum of five years after the relationship ends.
What documents you need for KYB (checklist)
KYB providers commonly request the following at onboarding. The company documents establish the entity; the individual documents support UBO and director verification. Financial statements are usually requested only where enhanced due diligence applies.
- Certificate of incorporation
- Articles of association or governing documents
- Proof of registered address
- A recent registry extract or certificate of good standing or status
- Shareholder register and register of directors
- Identity documents for each UBO, director, and authorised signatory
- Financial statements (usually only where enhanced due diligence applies)
Common failure modes
Most KYB failures are not exotic. They come from trusting a registry too much, stopping at the company, or treating verification as a one-off.
- Shell companies. A corporate wrapper with no real operations, used to hide the beneficial owner or launder funds, spotted by the step 6 red flags.
- Stale or unverified registry data. Registries record what was filed, not what is true. Companies House's own disclaimer and the ECCTA reforms exist because of this. Verifying against a registry without corroboration gives false confidence.
- Cross-border gaps. No single global source, US 50-state fragmentation, uneven EU beneficial-ownership access, and differing number formats mean multi-jurisdiction chains fall through the cracks.
- An EIN is not proof of incorporation. A tax number proves tax registration, not that a company was legally formed. Confirm incorporation against the incorporating registry.
- Skipping the control prong. Screening 25 per cent shareholders but missing a controlling nominee or senior manager who is the real UBO.
- Treating KYB as a one-off. No ongoing monitoring, so a clean onboarding becomes a stale, non-compliant record.
How long KYB takes: manual versus automated
Manual KYB is slow and repetitive because the same data is re-checked across disconnected systems. Independent estimates put a manual business verification at more than two weeks, and full corporate or SME onboarding commonly at 90 to 120 days, driven largely by ownership tracing. Automation compresses this by pulling registries, resolving ownership graphs, and running screening in parallel. Vendor case studies claim large reductions, but those are self-reported single-customer figures and should be read as such, not as industry norms.
| Stage | Manual | Automated (Zenoo's own measured figures) |
|---|---|---|
| Company dossier (steps 1 to 3) | 2 to 4 hours to compile a structured company dossier by hand | Under 60 seconds for a 50-plus-field dossier via the KYB Researcher agent |
| Full KYB pipeline (steps 1 to 4) | 3 to 5 business days end to end | Under 30 minutes, discovering 2 to 4 times more persons by cross-referencing multiple sources |
| Alert disposition (step 5) | 20 to 45 minutes per screening alert | 2 to 3 minutes, with up to 80 per cent of alerts pre-classified |
KYB by sector (marketplaces, fintech, banking)
The seven steps are the same everywhere, but the pressure points differ by sector.
- Marketplaces and seller onboarding. Platforms must verify each seller's business and ownership at scale and at speed, without a two-week manual process killing conversion. B2B marketplaces are singled out for a supplier-verification gap because they onboard many businesses fast, and cross-border platforms must still reach the ultimate ownership of each seller.
- Fintech and Banking-as-a-Service. Sponsor banks inherit compliance risk from every business their fintech partners onboard, so KYB now covers three layers: the partner, the partner's downstream business customers, and the UBOs behind both. This nested KYB was a named theme in 2024 to 2025 BaaS enforcement, where regulators cited failure to identify beneficial owners and weak downstream due diligence.
- Banking (corporate). The heaviest ownership-tracing burden, the longest timelines, and the tightest EDD expectations, which is why corporate onboarding sits at the 90 to 120 day end.
The rules behind KYB (FATF, US, EU, UK)
Regulation sits behind KYB rather than being the focus of the process. Keep it light and follow the glossary and UBO pages for depth. The 2025 to 2026 items below moved recently and are worth re-checking at the point of use.
Globally, FATF Recommendation 10 sets customer due diligence for legal persons, and Recommendations 24 and 25 govern beneficial-ownership transparency for legal persons and arrangements. In the US, the BSA and USA PATRIOT Act CDD Rule still require banks to identify legal-entity beneficial owners under the 25 per cent ownership prong and the control prong, while the Corporate Transparency Act's separate BOI reporting rule was cut back in March 2025 so that US-formed entities are exempt and only foreign reporting companies file. In the EU, the AML Regulation (EU) 2024/1624 applies from 10 July 2027 with a harmonised 25 per cent threshold, AMLD6 governs register access on a legitimate-interest basis, and the AML Authority (AMLA) is standing up. In the UK, the Money Laundering Regulations 2017 set the CDD duty, and the Economic Crime and Corporate Transparency Act 2023 is adding mandatory identity verification at Companies House, phased in from November 2025.
Where orchestration fits: your providers plus Zenoo
The seven steps depend on different data providers: a registry source per jurisdiction, a UBO and ownership data provider, one or more screening providers, and a monitoring feed. Most teams stitch these together themselves. The average financial institution uses 4.7 verification providers, and most compliance teams stitch together 6 to 8 disconnected tools. Zenoo is an orchestration platform: it connects the providers you choose behind one integration, one policy engine, and one audit trail, so the seven steps run as one workflow instead of seven manual handoffs. See the KYB use case and the vendor marketplace.
Where Zenoo genuinely helps, framed as Zenoo's own measured figures: for steps 1 to 4, the KYB Researcher agent compiles a 50-plus-field company dossier in under 60 seconds versus 2 to 4 hours manually, and the full KYB pipeline runs registry lookup, ownership graphing, and UBO discovery end to end in under 30 minutes versus 3 to 5 business days, discovering 2 to 4 times more persons by cross-referencing multiple sources. For step 5, Zenoo routes sanctions, PEP, and adverse-media checks to your chosen providers with failover and runs them in parallel, with alert pre-classification dispositioning up to 80 per cent of alerts and cutting per-alert time from 20 to 45 minutes to 2 to 3 minutes. For step 6, the Policy Parser turns a written KYB policy into structured risk rules in under 5 minutes, and a 209-country risk database with 16 indicators per country supports the risk assessment and EDD triggers. For step 7, continuous re-screening plus one immutable audit trail (32 event types across 8 categories) gives examiners a single evidence record across every provider.
Honest scope
What Zenoo does not solve
Zenoo does not itself hold a company registry, publish a sanctions or PEP list, or verify a passport; those come from the providers it orchestrates. If your underlying registry or ownership data is thin, or a jurisdiction's beneficial-ownership register is closed, Zenoo cannot invent the data. It does not make you compliant on its own; it helps you execute and evidence the process a human still signs off. See KYB orchestration for how this works in practice.
Where this fits, honestly
From reading about it to running it.
Zenoo orchestrates your registry, UBO, and screening providers so the seven steps run behind one integration, one policy engine, and one audit trail, instead of seven manual handoffs. AI agents handle UBO discovery and continuous monitoring, and every check lands in a single evidence record. Your providers plus Zenoo.
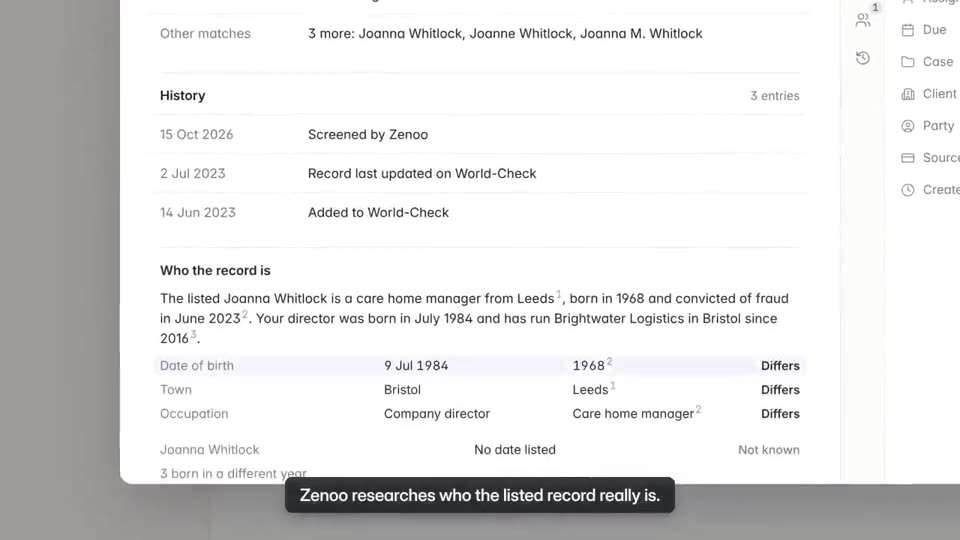
A live Compliance Hub with fictional data. Nothing you do is saved.